Indonesia’s GDP is expected to expand by 5.2% this year.
Public activity restrictions have eased and more shoppers will visit shopping malls.
Retail malls are set to benefit from low virus cases, renewed consumer optimism and a higher level of consumer spending.
We think the LMRTSP 7.250% 19Jun2024 Corp (USD) has an attractive bond yield.
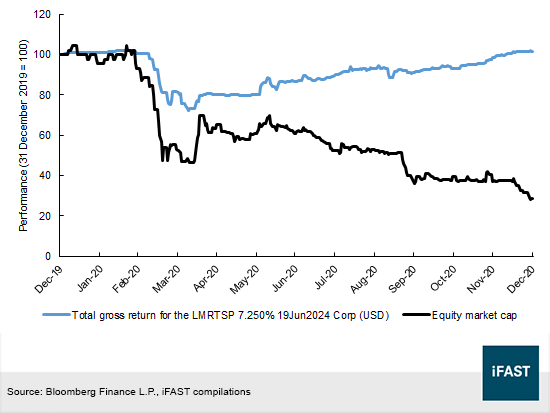
In 2020, the LMRTSP 7.250% 19Jun2024 Corp (USD) outperformed shares of Lippo Malls Indonesia Retail Trust (“LMIRT”). As seen in Figure 1, bondholders ended the year with a positive total return (bond price appreciation + accrued interest) of 1.62% before fees, but shareholders made significant losses.
LMIRT faced challenging business conditions in 2020, as Indonesian authorities imposed strict movement restrictions. Shopping malls were closed and shoppers could only travel to malls for essential activities. LMIRT made losses and the market value of its shares underperformed its 2024 bonds.
Figure 1: Performance of the LMRTSP 7.25% 2024's vs LMIRT shares
About LMIRT
LMIRT is one of Indonesia’s largest retail property owners. It is the only Indonesian retail real estate investment trust listed on the Singapore Exchange. As of 30 September 2021, the REIT managed 22 malls and 7 retail spaces, most of which are located across the Greater Jakarta, Bandung and Yogyakarta regions. LMIRT is rated ‘B1’ by Moody’s and ‘B+’ by Fitch Ratings.
Lippo Karawaci is the LMIRT’s sponsor. With a notable development track record, Lippo Karawaci is the market leader in mixed-use integrated developments with the largest land bank in Indonesia. The sponsor owns and/or manages 56 retail malls. As at 2 December 2021, Lippo Karawaci had a 47.29% interest in the REIT.
Improving economic conditions
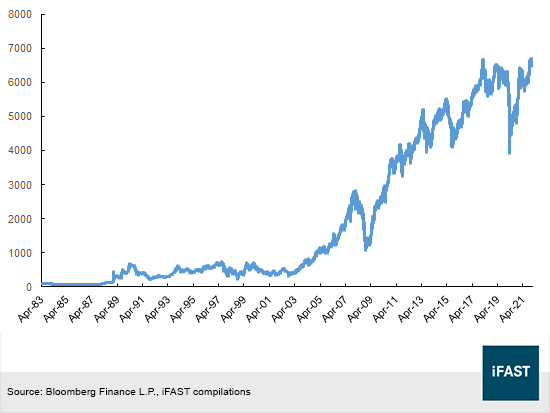
Indonesia’s economy is growing and many Indonesian companies have witnessed an improvement in earnings. The Jakarta Composite Index increased 9.4% by the end of 2021. In November last year, the equity benchmark breached its historical high and has since remained around that level (Figure 2).
Figure 2: Jakarta Composite Index
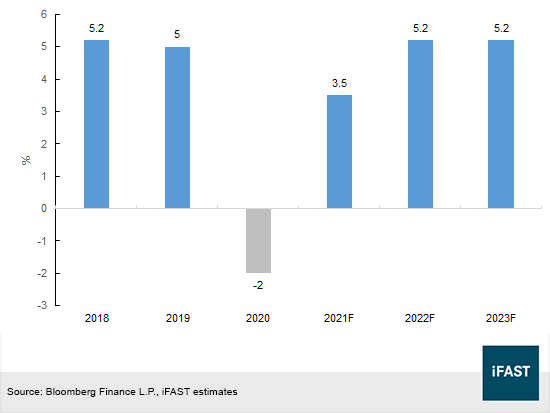
In spite of high equity prices, our macro team holds an optimistic view towards Indonesia’s economic prospects. The country’s GDP should continue to follow its upward trajectory path. As for its yearly growth projections, Indonesia is expected to end 2021 with a growth of 3.50% while a stronger pace of 5.20% is expected in 2022 (Figure 3).
Figure 3: GDP growth forecast
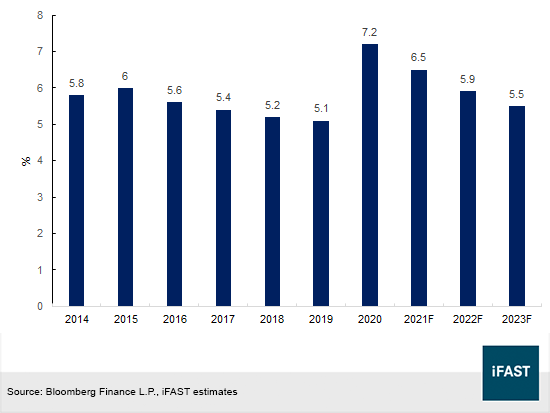
Economic growth is supported by a healthier labour market, which is anticipated to expand further as companies increase their hiring activities. Indonesia’s unemployment rate spiked to 7.2% in 2020 but is forecasted to fall to 5.9% by the end of this year (Figure 4).
Figure 4: Indonesia's unemployment rate
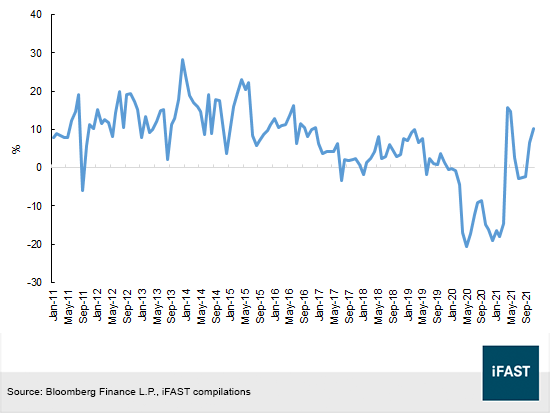
Indonesia’s retail sales jumped more than 10% YoY in November. In a Bank Indonesia poll, retailers saw stronger retail sales from fuels, food, beverages, and tobacco. Poll respondents saw milder inflationary pressure in January this year but inflation is likely to rise in April given the seasonal jump in demand during the fasting month of Ramadan.
Figure 5: Change in retail sales YoY according to central bank's survey
Indonesia’s new daily cases have dropped to the hundreds (Figure 6). A government commissioned survey found that nearly 9 in 10 Indonesians developed antibodies against Covid-19, even as the country lagged behind its Asian neighbours in vaccination rates. A higher herd immunity level could help Southeast Asia’s biggest economy to maintain its growth momentum. Omicron cases are surging but the variant is said to be less severe.
Figure 6: Daily new Covid-19 cases in Indonesia
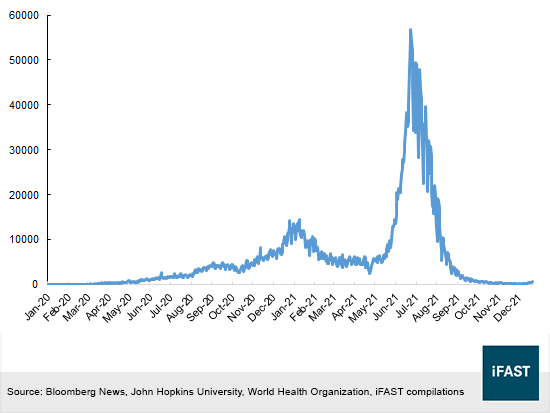
Set against a backdrop of low Covid-19 case counts, authorities have recently lifted travel restrictions. Movement curbs on unvaccinated individuals have been lifted, while restrictions on domestic air travel has ended. As of 5 December 2021, 53% of Indonesia’s population has received their first vaccination dose while 42% of the broader population is fully vaccinated. Normalcy is returning in the country and improving consumer confidence will likely boost Indonesian retailer sales.
Stronger operating results
LMIRT has witnessed a recovery in its operating results. During the third quarter ended 30 September 2021 (“3Q21”), net property income increased by 31.5% YoY to SGD 17.3m. Total loss improved significantly from a loss of SGD 191.1m in 3Q20 to a loss of SGD 0.7m in 3Q21.
The REIT reported a better financial performance in spite of the closure of certain malls and shorter operating hours.
Now that restrictions have been eased, we should be expecting higher foot traffic in the first quarter of this year. Management said that they were cautiously optimistic and would be looking to reduce its tenant support measures, especially in better performing malls.
Figure 7: Visitor traffic in October of each year
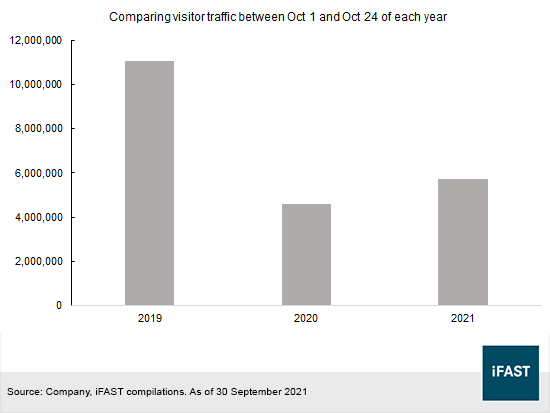
More shoppers have been visiting the malls within the portfolio. In October 2021, traffic recovered to approximately 52% (5.7m over 11.1m) of 2019 levels. Some malls have experienced better footfall. Traffic in malls like Sun Plaza and Lippo Plaza Kendari have seen traffic rebound to 94% and 71.4% of pre-Covid levels.
LMIRT has a weighted average lease expiry (WALE) of 3.3 years as at 30 September 2021. There is a healthy mix of long term anchor leases and shorter term leases for non-anchor tenants, which provide both stability and growth potential.
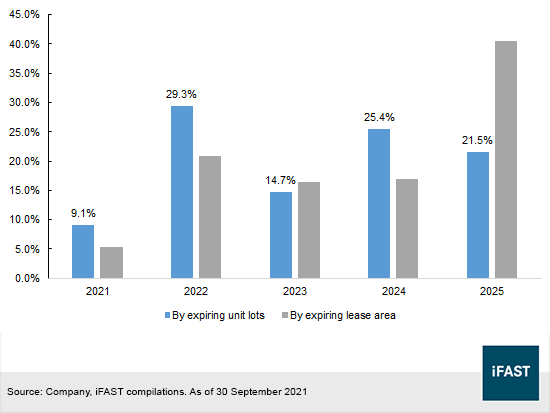
During the nine months ended 30 September 2021 (“9M21”), the REIT recorded a positive average rental reversion of +2.1%. With a better outlook for retailers, we believe that the REIT should be able to negotiate for higher rental rates from tenants. 29.3% of the leases are expiring this year and the REIT should continue to report positive rental reversions.
Figure 8: Percentage of leases expiring by years
Furthermore, LMIRT has no refinancing requirements until November 2022. The amount of liquidity – SGD 133.2m of cash and cash equivalents as at 3Q21 is adequate enough to cover borrowings until perhaps the first quarter of 2023. We do not foresee a high refinancing risk as we believe that the REIT has good support from its sponsor. Lippo Malls Indonesia Retail Trust received waivers for the financial covenants for some of their facilities. And that signals some creditor support as well.
LMIRT has an adequate credit profile. As disclosed by the trust, total gross borrowings and deferred payments added to SGD 859.4m as at 30 September 2021. When expressed as a ratio over its deposited property, the leverage ratio was 42.3% - slightly higher than 41.9% on 31 December 2020 but at this level, the leverage ratio is within the MAS limit of 50%. Interest coverage ratio is still comfortable at 1.7x at 30 September 2021 (31 December 2020: 1.8x).
Relative valuation
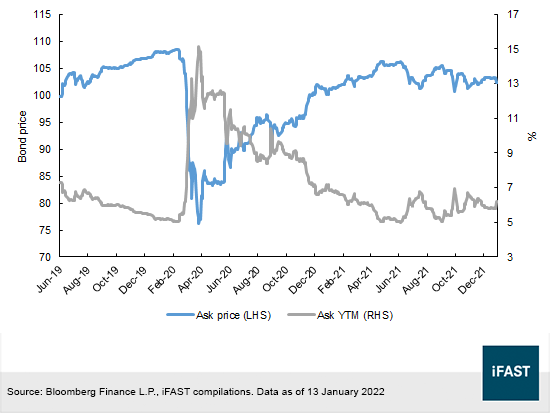
LMIRT’s USD senior unsecured notes and SGD perpetual securities are offering some of the highest yields among SGD REIT bonds. We think the LMRTSP 7.250% 19Jun2024 Corp (USD) is attractive with an ask yield to worst (“YTW”) of 6.29%. Investors may also consider the LMRTSP 7.500% 09Feb2026 Corp (USD) at its YTW of 6.93% but should be mindful of interest rate risks as market watchers are expecting three or more rate hikes from the Federal Reserve this year.
Table 1: LMIRT's outstanding bonds and perpetual securities
|
|
Amount outstanding |
Rank |
Moody’s rating |
Fitch rating |
Indicative ask price |
Indicative yield-to-worst |
|
LMRTSP 7.500% 09Feb2026 Corp (USD) |
USD 200m |
Senior Unsecured |
‘B1’ |
‘B+’ |
101.97 |
6.93% |
|
LMRTSP 7.250% 19Jun2024 Corp (USD) |
USD 250m |
Senior Unsecured |
‘B1’ |
‘B+’ |
102.13 |
6.29% |
|
LMRTSP 6.600% Perpetual Corp (SGD) |
SGD 120m |
Subordinated |
NA |
NA |
60.5* |
10.93%* |
|
LMRTSP 6.4751% Perpetual Corp (SGD) |
SGD 140m |
Subordinated |
NA |
NA |
83.90 |
8.25% |
| Source: Bloomberg Finance L.P., iFAST compilations. As of 13 January 2022. *Offer on Bond Express | ||||||
Figure 9: Ask price and yield-to-maturity for the LMRTSP 7.25% 2024's
LMIRT is unlikely to redeem the LMRTSP 6.4751% Perpetual Corp (SGD) in March and September 2022. The LMRTSP 6.600% Perpetual Corp (SGD) is redeemable on its first call date on 19 December 2022, but we think that the issuer is not likely to call back the notes. Both the 6.4751% and 6.600% perpetual notes face an extension risk but there is a higher probability of call for the LMRTSP 6.6% notes due to its smaller outstanding amount and higher reset rate.
The terms and conditions of the perpetual securities allow LMIRT to defer distribution payments, on a non-cumulative basis. Hence, a distribution deferral will not constitute an event of default.
Besides the non-cumulative deferral clause, a dividend stopper covenant is also applicable. In addition, perpetual note holders are subjected to restricted payment covenants in the senior USD bonds.
Will LMIRT bonds outperform its stock in 2022?
Yes, we believe that the LMRTSP 7.250% 19Jun2024 Corp (USD) will outperform its shares in 2022 on a recovering economic climate, increased shopper footfall, strong shareholder support and good refinancing ability. Indonesia’s economic growth for 2022 is projected to exceed that of 2021. We will likely see more business activity, and with the relaxing of travel restrictions, higher consumer spending is expected given the low number of Covid-19 cases. Visitor traffic to LMIRT’s shopping malls should also recover. Therefore, the bond has an attractive yield to worst of 6.29%.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in LMRTSP 6.600% Perpetual Corp (SGD) and FIRTSP 4.9817% Perpetual Corp (SGD). The analyst who produced this report hold a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!